Economic News
Subscribe →
HomeMonetary PolicyFiscalTradeRegulationBankingEconomic DataAbout
Vol. 02 · New Zealand
SUNDAY 20/09/2026
Iss. 2026 / 39
Economic News

Balanced. Independent. Informed.

Sections

  • Monetary Policy
  • Fiscal
  • Trade
  • Regulation
  • Banking
  • Economic Data

Subscribe

  • Free email
  • Email preferences
  • RSS feed

Company

  • About
  • Privacy policy

About

Economic News is an independent New Zealand publication covering monetary policy, markets, the public finances and the wider economy.

© 2026 Economic News Limited
.

Live
ECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZECONOMIC NEWS NZ
FMA · CCCFA REGULATION TRANSFER

FMA Takes Over CCCFA Regulation from Commerce Commission on 1 July 2026

The Financial Markets Authority will assume regulatory responsibility for the Credit Contracts and Consumer Finance Act 2003 from the Commerce Commission on 1 July 2026.

Regulation Desk04/06/2026 · 12:55 NZT6 min read
RegulationBreaking
RD
Regulation Desk
Regulation and Markets Conduct Reporter · 04/06/2026 · 12:55 NZT · 6 min read
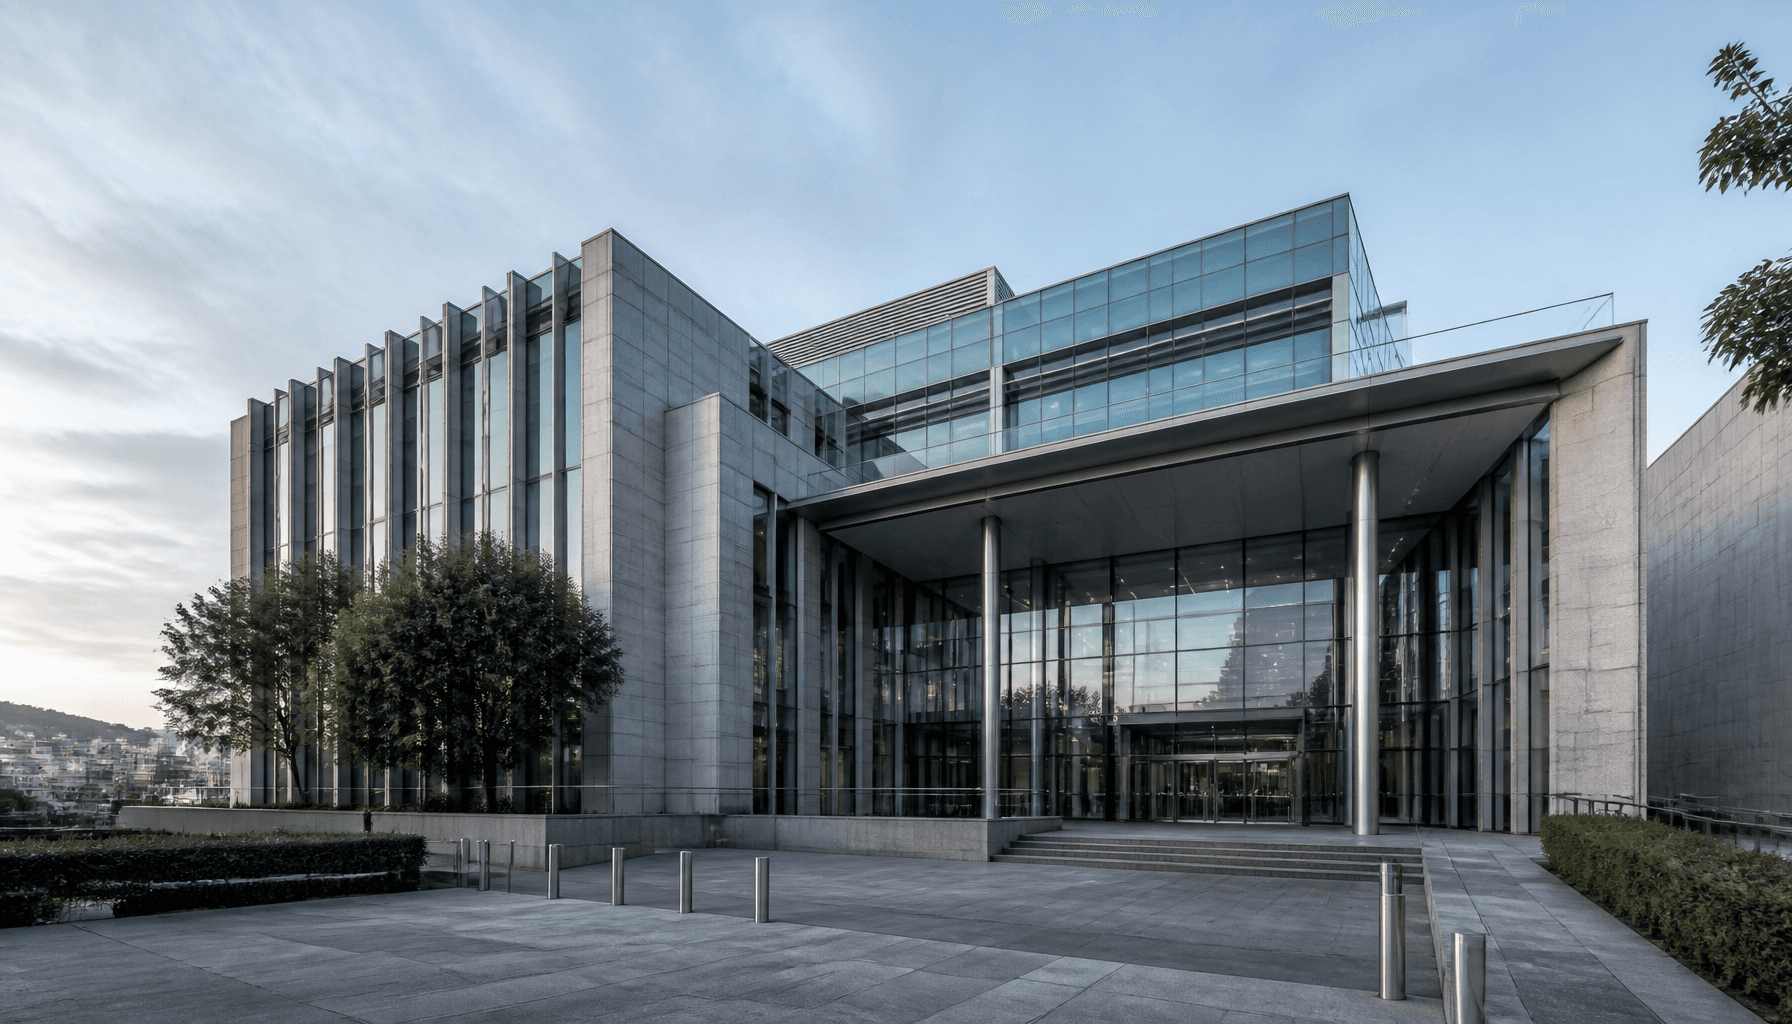
FMA building on Wellington's Lambton Quay on an overcast morning

At a glance

From 1 July 2026 the FMA becomes New Zealand's single conduct regulator for consumer credit, absorbing roughly 450 non-bank lenders and new stop-order powers from the Commerce Commission.

Key stats

Transfer date
1 Jul 2026
FMA takes over from ComCom
Bill third reading
28 May 2026
Amendment Bill passed
Cabinet approval
Mar 2024
decision to transfer
Total lenders
~500
under CCCFA regime
Non-bank share
~90%
of total lenders
CCCFA amendments
31 Jul 2024
affordability rules revoked

Sources cited

  • Credit Contracts and Consumer Finance Act (CCCFA) — Financial Markets Authority
  • Transfer of responsibility for regulation of consumer credit — Commerce Commission
  • FMA welcomes third reading of Bill, prepares for transfer of regulatory responsibility for consumer credit — Financial Markets Authority
  • Government announces decisions on financial services reforms — Buddle Findlay
  • Changes to credit laws — Commerce Commission
  • CCCFA transfer frequently asked questions — Financial Markets Authority

Free

New Zealand's economy, straight to your inbox.

By subscribing you accept our privacy policy.

More from regulation

Reserve Bank of New Zealand headquarters exterior in early morning light
Regulation · 18/09/2026 · 08:43 NZT

Cabinet clears RBNZ prudential levy consultation; banks face multi-million bills

Cabinet’s Economic Policy Committee has formally authorised public consultation on a prudential levy to shift Reserve Bank supervision costs onto banks, insurers and market infrastructure operators from 2027/28.

Regulation Desk·18/09/2026 · 08:43 NZT·7 min
Wellington government office desk with stacked performance reports and a laptop showing blank charts
Fiscal · 18/09/2026 · 08:42 NZT

Cabinet backs FEC performance-reporting shifts in principle; design costs deferred to 2027

Cabinet has agreed in principle to three shifts in public performance reporting sought by the Finance and Expenditure Committee, while parking detailed design and costings until 2027.

Fiscal Desk·18/09/2026 · 08:42 NZT·5 min
Dawn view of a Northland fuel terminal tank farm and empty import jetty
Economic Data · 18/09/2026 · 05:53 NZT

Paper cover versus pump cover: NZ fuel stocks and dual chokepoint risk

MBIE’s 6 September snapshot shows 51.7 days of petrol cover on paper. Only 34.5 of those days sit onshore. Eight of nine ships still float outside the EEZ, and sequential Hormuz then Red Sea stress is already priced into $3-plus petrol.

Analysis Desk·18/09/2026 · 05:53 NZT·14 min

All regulation →

The Financial Markets Authority will assume regulatory responsibility for the Credit Contracts and Consumer Finance Act 2003 from the Commerce Commission on 1 July 2026.

The transfer follows the Credit Contracts and Consumer Finance Amendment Bill passing its third reading on 30 May 2026, according to the FMA's own press release and multiple news sources. Cabinet approved the move in March 2024. An Amendment Paper released by the Minister of Commerce and Consumer Affairs on 31 March 2026 set the 1 July 2026 commencement date.

FMA Executive Director, Licensing and Conduct Supervision, Clare Bolingford described the approach as engagement-led. She said the regulator will work closely with lenders and stakeholders to deliver fair outcomes.

"As an engagement-led regulator, we'll work closely with lenders and industry stakeholders to ensure the financial services sector delivers fair outcomes and earns the trust of businesses, consumers, and investors," Bolingford said.

The FMA gains new tools including the power to issue stop-orders with immediate effect — a tool the Commerce Commission did not have. Bolingford said this allows faster responses to misconduct than litigation alone, enabling quicker remediation for customers when something goes wrong, without the need to take every case through a lengthy court process.

Licensing regime and lender numbers

According to RNZ reporting, non-bank lenders make up about 90 percent of the roughly 500 lenders under the regime. Existing providers will receive automatic FMA market services licences. New entrants must apply.

"Introducing a licensing regime for lenders will give the FMA more ways to monitor and supervise lending activity, and will provide a wider set of regulatory tools to support effective oversight," Bolingford said.

The Commerce Commission has also welcomed the transition. Acting General Manager, Office of the Board and Chief Executive, Sarah Bartlett said the Commission has been working closely with the FMA since the initial announcement to ensure a smooth and well-governed handover.

"The passage of the Bill provides clarity for industry and consumers, and we are focused on supporting a seamless handover of responsibilities to the FMA. This includes the transfer of our experienced credit team to the FMA, where they will continue this important work," Bartlett said.

The Commission is reminding lenders and consumers to continue engaging with it on CCCFA matters until the 1 July cutover date.

A contentious history

The CCCFA dates to the mid-1970s. A 2021 tightening of disclosure and responsible lending rules led lenders to adopt more cautious practices. Amendments effective 31 July 2024, as recorded by the Commerce Commission, revoked prescriptive affordability assessments while retaining the responsible lending principle.

The FMA and Commerce Commission have prepared for two years. This included staff transfers and data governance protocols. The change supports the separation of prudential supervision at the Reserve Bank of New Zealand from conduct oversight at the FMA. It aligns credit regulation with the Financial Markets Conduct Act 2013 framework.

In a formal statement carried by Scoop and Mirage News, Bolingford said: "This isn't just a change in oversight — it's a move toward a more connected and coordinated approach to regulating financial market conduct. By aligning credit regulation with broader financial services, we're creating a framework that better supports responsible lending and consumer protection."

Lenders and consumers can expect continued enforcement powers alongside the engagement focus. The FMA has stated it will use its full range of tools to address misconduct.