Revenue Minister Simon Watts has introduced the omnibus Taxation Bill to enact remaining Budget 2026 tax measures, including FBT vehicle simplification and FIF threshold changes, with Parliament’s dissolution set for 1 October.
The Government on 10 September 2026 introduced the Taxation (Annual Rates for 2026–27, FBT Simplification, Foreign Investment Funds, and Remedial Measures) Bill into the House. Revenue Minister Simon Watts said the Bill will lower compliance costs and simplify rules for employers and investors.
Parliament’s final adjournment is expected around 24 September. Dissolution of the 54th Parliament is scheduled for 1 October 2026. Unfinished bills lapse on dissolution and require reinstatement by the next Parliament.
Watts framed the package as growth-friendly simplification rather than a broad tax cut.
“My aim is for a world-leading tax system, and these sensible changes bring us a step closer to that. For fringe benefit tax, we’re proposing a much simpler ‘close enough is good enough’ approach to employer-provided vehicles,” he said in a 10 September government release.
The Bill carries the bulk of Budget 2026 tax initiatives not already enacted under urgency in the Taxation (Budget Measures) Act 2026, which received Royal assent on 5 June 2026. FBT motor-vehicle changes would apply to benefits provided after 1 April 2027. FIF reforms are designed to apply from 1 April 2026 for the 2026–27 year once enacted.
FBT: categories replace day-counting
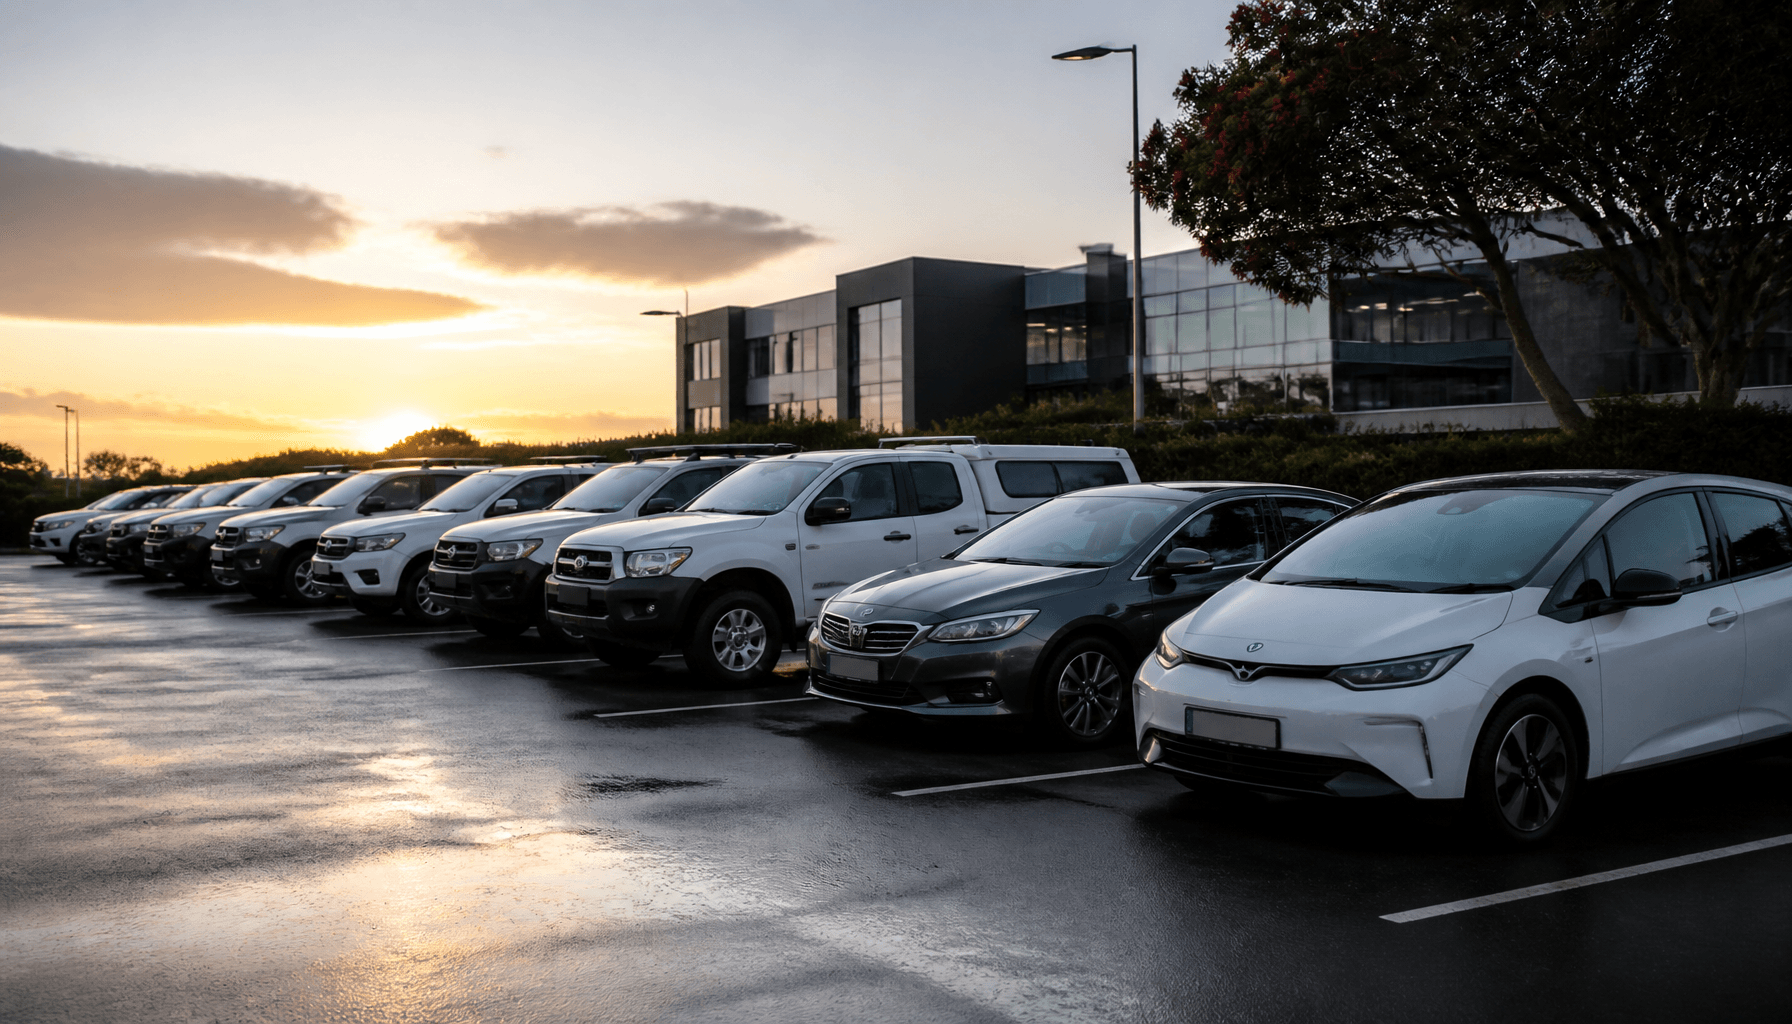
Current FBT rules tax employer vehicles largely by private-use days available, with a work-related vehicle exemption long criticised for distorting fleets toward utes. Officials propose six categories keyed to expected private use, branding and access. Inclusion rates run from 100% for pure perk vehicles down to 0% for multi-site branded commute vehicles and true pool cars.
Valuation percentages on cost or tax book value would fall for hybrids and electric vehicles to reflect lower running costs. Budget 2026 scored the motor-vehicle FBT package at just $0.6 million over the forecast period on the Tax Policy Scorecard.
Deloitte tax partner Robyn Walker told RNZ the new rules would be easier to comply with and fairer. She said current settings create a tax bias toward utes for home-to-work travel and punish higher-cost EVs when cost-linked valuation applies. Under the proposal, use—not vehicle type—would drive the liability, putting utes, cars and EVs on equal footing for lower FBT eligibility.
“Currently, the criticism of the FBT rules has been there is an incentive for people to buy utes because a ute was a way into an FBT exemption if the vehicle was only used for home-to-work travel. Utes are the biggest sellers in New Zealand... there would definitely have been a tax influence to that... a normal car wouldn't have got the same exemption.”
BDO Associate Director Sandita Singh said the reforms are the most practical FBT simplification in years, but businesses must reassess classifications. Remuneration-package perk vehicles may face higher FBT. Policies, branding and classification evidence should be prepared well before 1 April 2027.
FIF: de minimis doubles; RAM widens
Foreign investment fund rules would lift the cost-based de minimis from $50,000—unchanged since 2000—to $100,000, which Inland Revenue says fully accounts for CPI since 2000. The revenue account method for qualifying unlisted foreign shares, taxing realised gains with a 30% discount plus dividends, would open to all New Zealand residents, not mainly recent migrants.
Budget materials put the FIF fiscal cost at about $72.5 million over the forecast period. Walker noted the threshold change is intended to be retrospective to 1 April 2026, so investors could lift cost bases toward $100,000 now—but legislation is not yet law and election risk remains. Enactment is expected around March 2027 if the Bill survives the calendar.
“The threshold change is going to be retrospective back to April 1, 2026… So people could increase their investments up to that $100,000 threshold now, but obviously they run the risk that the legislation hasn't actually been enacted. We would expect the laws to go through the normal process, subject to anything major happening at the election, and be enacted in March 2027.”
Below the de minimis, investors generally face tax on dividends (and revenue-account gains), not annual unrealised FDR-style income. The threshold is cost, not market value, so buy-and-hold appreciation under the limit does not alone trigger FIF.
Wider Bill and fiscal track
The Bill also covers in-year R&D Tax Incentive payments, a cut in the non-administrative internal software cap from $25 million to $3 million (net RDTI savings about $84.6 million), not-for-profit filing and deduction relief, donation administration ease, and overseas student-loan enforcement. Bank thin-capitalisation tightening and a separate prudential levy sit nearby on the integrity side.
Treasury’s Budget Economic and Fiscal Update 2026 still shows large near-term OBEGALx deficits: $11.9 billion (2.6% of GDP) in 2025/26 and $11.4 billion (2.4% of GDP) in 2026/27, before a planned path to surplus by 2028/29. The tax package is incremental and scorecard-managed inside that consolidation, not a structural revenue reset.
What employers and investors should do now
Employers with fleets should map vehicles to the proposed categories, document private-use expectations and branding, and update FBT systems for a 1 April 2027 start—without treating the Bill as law until Royal assent. Offshore investors near the $50,000 cost line should weigh any pre-enactment top-up against legislative and election risk; current law remains the $50,000 de minimis and day-counting FBT.
- Map fleet vehicles against the six proposed FBT categories and document private-use expectations and branding evidence.
- Update payroll and FBT systems ahead of the 1 April 2027 start date, without assuming the Bill is already law.
- Offshore investors near the $50,000 cost line should weigh pre-enactment top-ups against legislative and election risk.
If the Bill lapses at dissolution and is not promptly reinstated, 2026–27 FIF returns and April 2027 FBT systems work face extended uncertainty. Select committee scrutiny, if the measure proceeds, will test category edges, branding standards, RAM boundaries and transitional elections. Until assent, compliance reduction remains a Budget promise, not statute.